The Role of Cooperative Credit Unions in Modern Finance: Community, Ethics, and Inclusion
Modern finance often gets reduced to interest rates, quarterly earnings, and shareholder returns. But a quieter, older tradition has been running alongside it for centuries — one built on mutual aid, democratic governance, and the idea that money should serve people, not the other way around. Cooperative credit unions embody that tradition, and their relevance in today's financial landscape is growing, not shrinking.
What Is a Cooperative Credit Union?
A cooperative credit union is a member-owned financial institution that provides savings, loans, and financial services to its members — not to outside investors. Every person who deposits money into a credit union becomes a part-owner, with an equal vote in how the institution is run, regardless of how much they've saved.
The founding logic is straightforward: pool resources among a defined community, then lend those resources back to members at fair terms. That community might be defined by geography, employer, profession, or shared identity. What matters is the bond — the common thread that ties members together and creates a foundation of trust.
Credit unions trace their modern form to 19th-century Germany, where Friedrich Wilhelm Raiffeisen developed rural cooperative lending societies to help farmers escape predatory moneylenders. The model spread globally because it addressed a universal problem: access to affordable credit for people the formal banking system ignored.
Today, credit union governance remains grounded in democratic member control. Boards are elected by members. Surplus funds are returned to members through better rates or lower fees, not distributed to external shareholders. This structural difference is not cosmetic — it fundamentally shapes every decision the institution makes.
How Credit Unions Differ from Traditional Banks
The main difference between credit unions and commercial banks is ownership and purpose. Banks answer to shareholders and prioritize profit; credit unions answer to their members and prioritize service.
This plays out in practical ways. Credit unions typically offer lower loan rates, higher savings returns, and fewer punitive fees than their commercial counterparts. Because there's no pressure to maximize profit margins for external investors, the institution can afford to price its products more fairly.
The profit-sharing model in credit unions means surplus earnings — what a bank would call profit — get redistributed. Sometimes this means dividends on savings accounts. Sometimes it means reduced loan interest. Sometimes it funds community programs or financial education. The surplus stays within the membership.
Commercial banks also operate under a fundamentally different incentive structure when it comes to risk. A bank's risk appetite is shaped by what generates the best return for shareholders. A credit union's risk decisions are shaped by what protects and serves members. That's not a subtle distinction — it drives everything from lending criteria to product design.
The Alignment Between Cooperative Credit and Islamic Finance Values
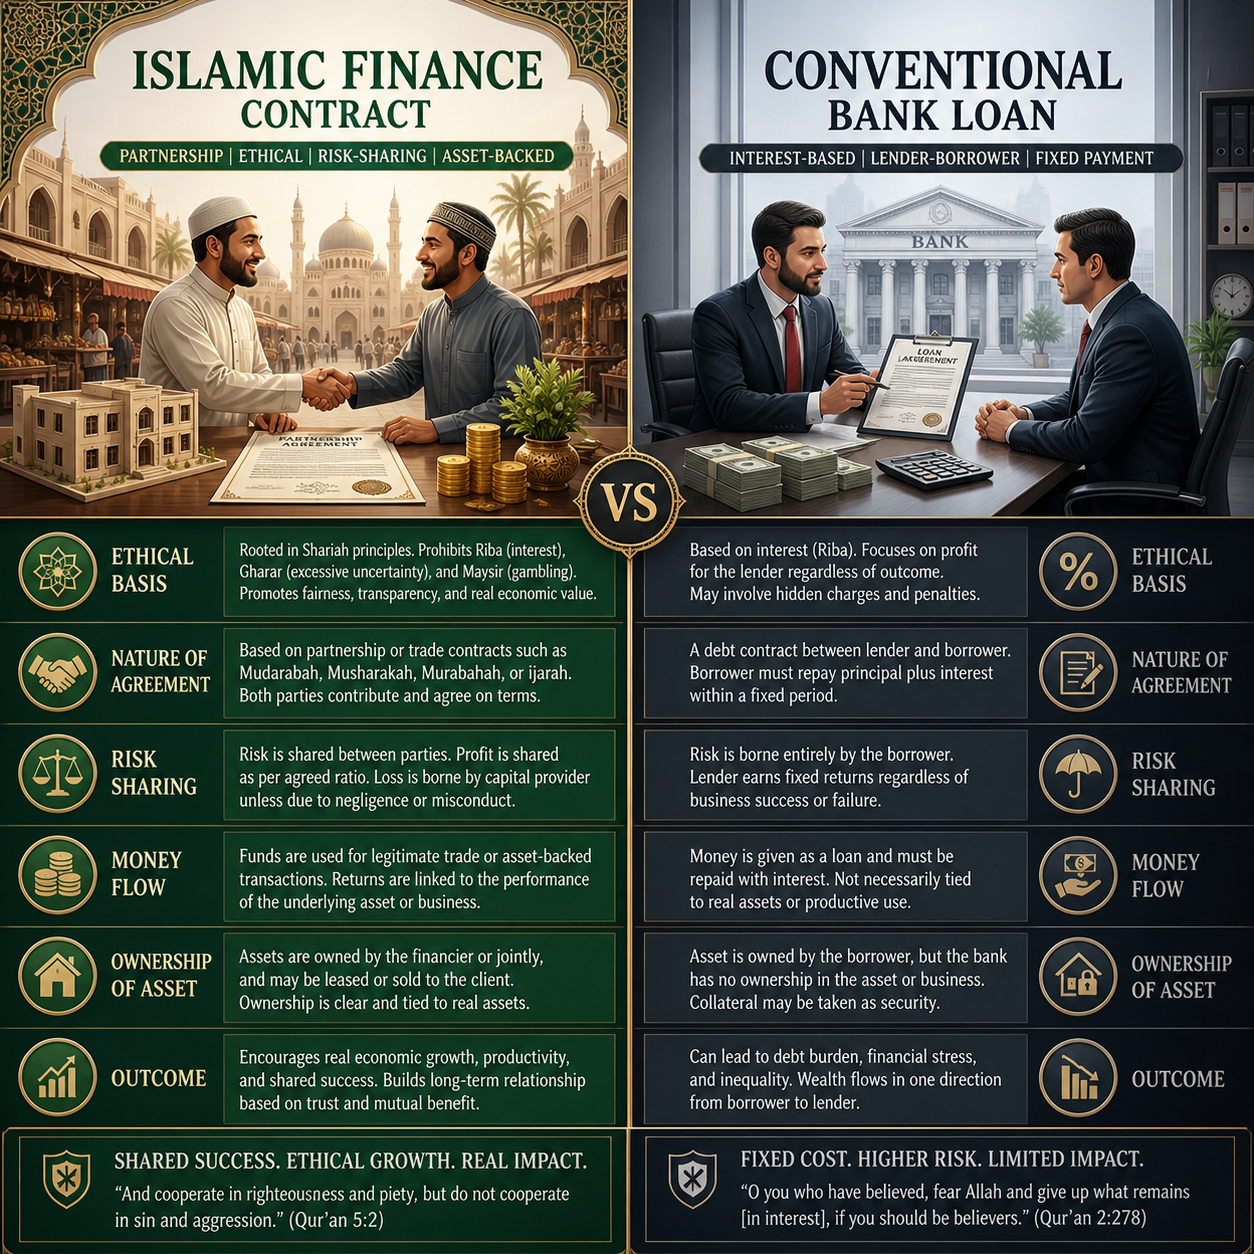
The ethical foundations of cooperative credit unions and Islamic finance principles share more common ground than most people realize. Both systems reject the idea that money itself should generate money through interest, and both place community welfare above individual profit extraction.
Islamic finance prohibits riba — the charging of interest — on the basis that it creates an exploitative relationship between lender and borrower. The lender profits regardless of the borrower's outcome; risk is not shared. Cooperative credit models push back against the same dynamic, even if they arrive at the conclusion through different philosophical routes.
The concept of mutual aid sits at the heart of both frameworks. In Islamic finance, this manifests through instruments like mudarabah (profit-sharing partnerships) and musharakah (joint venture arrangements), where returns depend on actual economic outcomes rather than predetermined interest charges. In cooperative credit, it manifests through member governance, shared risk, and reinvestment of surplus into the community.
Neither system is identical to the other. Islamic finance operates within a specific theological and legal framework that goes beyond what most credit unions formally adopt. But the philosophical overlap — avoiding exploitation, promoting shared risk, centering community welfare — is genuine and meaningful. For Muslims seeking ethical financial alternatives, understanding this overlap matters.
Interest-Free Lending Models Within Cooperative Frameworks
Some cooperative lenders and credit unions do offer interest-free lending products, particularly for small emergency loans or community development purposes. These models are more common than many people assume, and they serve a clear purpose: keeping financially vulnerable people out of high-cost debt traps.
The qard hasan concept in Islamic finance — a benevolent, interest-free loan given to someone in need — has a structural parallel in cooperative finance. Many credit unions operate emergency loan funds or hardship lending programs where no interest is charged, funded by member contributions or charitable reserves.
Community Development Financial Institutions (CDFIs) represent another model in this space. These organizations, which include many credit unions, are specifically designed to serve underserved markets with affordable credit. Some CDFIs have begun exploring Sharia-compliant financial products to better serve Muslim communities, recognizing that conventional loan products — even at low rates — may not meet the needs of members who avoid interest on religious grounds.
Choosing an interest-free or low-cost cooperative loan model means accepting certain constraints: smaller loan limits, more restricted eligibility, and sometimes longer processing times. But for someone choosing between a predatory payday lender and a cooperative interest-free loan, those constraints are a reasonable trade.
Financial Inclusion and the Social Impact of Credit Unions
Credit unions consistently reach people that conventional banks turn away. Financial inclusion — ensuring that everyone has access to affordable, appropriate financial services — is baked into the cooperative model, not bolted on as a corporate social responsibility afterthought.
Low-income households, immigrants, people with thin credit files, and residents of underserved communities often find that commercial banks either won't serve them or will do so only at punishing cost. Credit unions, because they're built around a defined membership community rather than profit optimization, have both the incentive and the flexibility to serve these groups.
The social impact extends beyond individual loan access. When a credit union reinvests surplus into its community — through financial literacy programs, small business support, or affordable mortgage products — it creates compounding benefits. Members build credit histories, develop savings habits, and gain access to financial tools that would otherwise remain out of reach.
Research consistently shows that community development finance institutions, including cooperative credit unions, generate measurable economic mobility in the communities they serve. This isn't charity — it's a structural outcome of a model designed around member welfare rather than shareholder returns.
Challenges Facing Cooperative Credit Unions Today
Cooperative credit unions face real pressures that can't be glossed over. Regulatory compliance costs have risen sharply, and smaller credit unions often lack the administrative capacity to absorb them without straining their operations.
Scalability is a persistent challenge. The same community-bond structure that makes credit unions trustworthy and mission-driven also limits their growth. A credit union built around a specific employer or neighborhood can't simply expand into new markets the way a commercial bank can.
Fintech companies have also entered the space with slick digital interfaces and competitive rates, attracting younger members who might otherwise have joined a credit union. Many credit unions have been slow to modernize their digital infrastructure, creating a perception gap — even when their products are objectively better for members.
There's also a consolidation trend. Smaller credit unions are merging at an accelerating rate, which can preserve financial viability but sometimes dilutes the community connection that made them valuable in the first place. Ethical banking requires ongoing commitment, not just structural design.
The Future of Cooperative Credit in a Modern Financial Landscape
Cooperative credit unions have a genuine path forward — but it requires deliberate evolution rather than passive continuity. The institutions that will thrive are those that combine their foundational values with modern delivery mechanisms.
Digital transformation is non-negotiable. Members expect mobile banking, instant transfers, and online loan applications. Credit unions that invest in these capabilities without abandoning their cooperative governance model can compete effectively with fintech alternatives while offering something fintech cannot: actual member ownership and democratic accountability.
The potential integration between cooperative credit frameworks and Islamic finance principles represents one of the more interesting opportunities in ethical finance. As Muslim populations grow in Western countries and demand for Sharia-compliant financial products increases, credit unions with flexible product design and community-centered values are well-positioned to fill that gap — provided they're willing to engage seriously with Islamic finance scholarship and develop appropriate products.
The World Council of Credit Unions has documented how cooperative financial models continue to expand globally, particularly in emerging economies where conventional banking infrastructure is thin. The solidarity economy principles that credit unions embody — mutual aid, shared risk, democratic control — are gaining renewed attention as people look for financial systems that serve human needs rather than abstract market metrics.
Credit unions won't replace conventional banks. But they don't need to. They need to remain what they've always been at their best: accessible, trustworthy, and genuinely oriented toward the people they serve.
Frequently Asked Questions
Are credit union loans interest-free?
Most credit union loans are not entirely interest-free, but they typically carry significantly lower interest rates than commercial banks. Some credit unions offer specific interest-free emergency loan products or hardship funds. Credit unions with Islamic finance-aligned programs may offer Sharia-compliant, interest-free loan products for qualifying members.
How is a credit union different from a bank in terms of ownership?
A credit union is owned by its members — the people who deposit money and take loans. Each member has one vote in governance decisions, regardless of account size. A commercial bank is owned by shareholders who may have no relationship with the bank as customers, and voting power is proportional to share ownership.
Can Muslims use cooperative credit unions as a halal finance option?
It depends on the specific credit union and its products. Standard credit union loans do involve interest, which conflicts with Islamic finance principles. However, some credit unions offer interest-free emergency loans or are developing Sharia-compliant products. Muslims should review specific product terms and consult with a qualified Islamic finance scholar before determining whether a particular product meets their requirements.
How do you join a cooperative credit union?
Eligibility for a credit union is based on a common bond — typically your employer, location, profession, or community affiliation. To join, you generally need to meet the eligibility criteria, complete an application, and open a savings account with a minimum deposit. Many credit unions have expanded their eligibility criteria in recent years, making membership more accessible.
What protections do credit union members have compared to bank customers?
In many countries, credit union deposits are protected by government-backed deposit insurance schemes equivalent to those covering bank deposits. In the United States, for example, the National Credit Union Administration (NCUA) insures deposits up to $250,000 per member — the same level as FDIC protection for bank customers. Members also have the added protection of democratic governance: they can vote on leadership and hold the institution accountable in ways that bank customers cannot.